Monday, January 14, 2013
Thursday, January 3, 2013
Indian Car Sales Figures - December 2012
| December 2012 Sales Figures - Pan India |
HIGHLIGHTS:
· Indian Auto Industry had a similar performance as our Indian Cricket Team - a combination of hits and misses. Sometimes you see a Silver lining (like Dhoni single handedly reviving the scores - similar to SUVs/MUVs being the saviors for the industry) and sometimes you see a freefall (like Indian openers vis-a-vis biggies such as GM, Tata, VW etc). Don't expect the things to better anytime soon.
· December was month of hefty schemes - all OEMs had the best to offer. This did not have much effect on the offtake figure of the Auto companies. Reason being focus on rationalizing the inventories and liquidation of old stocks. With 2012 stock piled up, picking up more vehicles wasn't the intent. However, VID (Vehicles - In - Demand) such as Swift, Innova, Dzire etc had the best run. December is usually a dull month in terms of Offtake; but the Dealer Retail is considered to be the best in the month - hence the end retail figures would project a total different story.
· The new Alto 800 has brought stability to the brand with its k10 sibling - figure of 26234 units offtake in the month of December is a true testimony of it.The brand has revived hopes for the entry level hatchbacks in the country. Swift & Dzire remain the best cash cows for the OEM - with minimal promotions and un-ending booking list - these brands are literally filling the pockets of the OEM and its channel partners without any sweat. Wagon R figures was a shocker - is a refresh on cards? And surprisingly A-star achieved 4 figure sales after 5 months! Ritz too wasn't able to provide much 'JOY' with its average faring - even the refreshed looks and launch of Auto Transmission couldn't generate much buzz. The petrol-only available models (Omni, Eeco) numbers still remain mystery - clearly explains the dominance of functionality and utility in any segment.
· Hyundai had a lack luster month. Its uber-cool i20 had its lowest offtake in past 10 months (5119 nos) - otherwise the model had been able to garner 7k units at an average. Even the fluidic Verna slipped to < 3k mark for the first time since April'11. However, Eon and i10 were the rescuer for the OEM. With an overall volumes of 26697 units, Hyundai's just 3.9k numbers ahead of M&M. Any glitch and the UV major would steal the second position from the Korean stalwart.
· Mahindra is the Maruti of the UV space – no wonder I'm re-instating the quote - while analysts were discussing the fall of Xylo, the Indian Automaker came up with Quanto built on the same Xylo platform! And Yes, M&M was able to gain consistent volumes; Food for thought - Quanto+Xylo = 4699 units! Now, that's Alternative Thinking. Verito faces the Deja vu situation - from over 2k units to near 1k units just within 4 months. The brand had aroused some hopes with its fresh avatar; but the consumer won't buy that. Its time for M&M to re-work on the branding and try something new. No month can judge the performance of the break-free Bolero. It has been able to maintain the consistency that OEMs couldn't even dream of - a simple hats off to the brand. Scorpio & XUV had its own set of issues - has the unstoppable Indian challenged their dominance? ;)
· Tata Motors probably gave the worst farewell to Mr. Ratan Tata. With such strong portfolio of cars, the de-growth of over 50% YoY just doesn't explain! Mr. Mistry & Mr. Slym have a lot to work on - not only on the products; but on the brand in overall.
· GM could not 'Sail' the high tides - the new hatchback failed to impress. And post its launch even the capable Beat has fallen to 2.9k figures from 4.5k average. Even Tavera with slight refresh and BS4 offering couldn't lure much buyers- but is still continuing its 1700 average figures. Also lets have a minute's silence in the memory of Aveo, Aveo UVA and Optra. The much capable cars were just let off.
· Duster's performance is matchable to Nasir Jamshed's contribution to the Pakistan team :p The lone performer is easily uplifting the Renault brand in India and the dealers are more than happy with their cash registers ringing month-on-month. The brand has put forward a stiff competition to the biggies from its divorced M&M stable (Scorpio & XUV). Even Scala is gaining ground on a monthly basis. Pulse, Koleos & Fluence still remains a bet.
· Toyota's dependence on Innova & Fortuner is increasing over time. The made-for-India Etios & Liva are losing its sheen and the offtake numbers are the testimony of it. Innova successfully makes it to the 7th best selling vehicle in December'12. Kudos! With just over 2k difference from the 4th slot (Tata Motors); Toyota may soon snatch the position in coming months.
list of Top 20 Brands of the month -
Tuesday, December 25, 2012
'Best or Nothing' inspired CLA sedan
In June 2010, Mercedes Benz had donned a new tagline - The Best or Nothing. The motto was to exemplify 'perfection, fascination & responsibility' as core values for the Brand. Also plans were made to launch 16 models based on the philosophy.
In last Auto Expo we saw the first preview of the A-Class -
The hatchback proportions added with the aggressive styling had stunned the auto enthusiasts. The design was an indication of the 'changing' face of Mercedes Benz. With its leadership being snatched by the newbies BMW & Audi, MB had to bring something radically new to regain its lost glory. And A class was the answer.
The car had earned a mammoth fan following across the globe and garnered 90,000 bookings in a very short period of time. This was the OEMs most successful launch till date. The vehicle was also perfect to re-establish MB for the growing countries as India, Brazil and China.
And the next step looks much more promising - A-class based sedan CLA
Derived of A-class, the CLA is poised to be sold as CLS younger sibling. The Style Coupe Concept Design has surely made the concept look a head-turner. With a length of 4.6 mtrs, the car seems very apt for the youth. This will also help the brand go ga-ga among youngsters. Appreciate the attempt by MB!
A whole gamut of products are planned to be designed around the car - a new 4-matic version along with an AMG version (CLA 45 AMG) could be expected in some time.
The car is set to be unveiled at the 2013 North American International Auto Expo to be hosted at Detroit. So, will the new offerings from the German giant ladder it back to the top? Seeing the products, i say Yes!
Sunday, December 23, 2012
Indian Bike Sales Figures
A snapshot of the performance of the Indian Two Wheeler Industry in past 6 months -
1. Hero Moto Corp:
Hero Moto Corp (HMC) has been the "Maruti" of the Indian 2 wheeler industry. Its aggressive marketing and rural stronghold had made it an indomitable force to reckon with. But in the past one year it had to experience major upheaval - be it in terms of dis-association with Honda or rising labour issues. Although at one point of time the brand was successful in maintaining its 5 Lakh sale continuously (Dec'11 - Jun'12); the rising petrol prices, inflation and strengthening competition has slowed down the 2-wheeler major. Post the break-up with Honda, HMC has been following the product-offensive strategy to intensify its portfolio - See Ignitor, Maestro, Impulse for examples. But the similarity of the upcoming models with Honda models has hindered it to create a mark of its own. Even the bread and butter model - Splendor has faced stiff competition with Bajaj's Discover and Honda's Dream Yuga. Notable is the sales of the Stunner inspired-Ignitor which is significantly higher than its Honda sibling (in Nov'12 Ignitor sales were 7351 units vis-a-vis 1379 untis of Stunner).However, Splendor & Passion still constitute to over 60% of HMC sales. It will be interesting to see how the company would fare in the coming months with Bajaj Auto all pepped up to launch its new 100 cc offering.
2. Bajaj Auto:
With the year-end falling in the two wheeler auto major had a MoM de-growth of over 13 percent (Nov'12 vs Oct'12). The Discover range has grown significantly in past 6 months. Discover even emerged as the world's largest selling bike (inclusive exports) in Oct'12 by de-throning the reigning Splendor. The Pulsar brand hasn't been able to gain much with the new Pulsar 200NS. Avenger though has been able to garner consistent sale of average 2.5k units. However, Platina hasn't got the recognition Bajaj had expected from it. This forced Bajaj Auto to launch Discover in 100 cc and made the auto major to launch a new 100 cc model (expected in first quarter of 2013).
3. Honda Motorcycle and Scooter India (HMSI):
HMSI has grown substantially in recent times. Time and again it has threatened Bajaj Auto of its second spot. With a dominating Scooter portfolio and growing Motorcycle range, Honda seems the most promising 2-wheeler manufacturer in India. The bike major has a proper product placement - starting with Dream Yuga in the lower-end with the top of the line CBR 250 leading the brand. And with Activa, Dio & Aviator in its kitty; it is easily garnering over a lakh sale from scooters itself.
4. TVS Motors
TVS Motors has lost the Scooter dominance and has given the segment to HMSI on a platter. Scooty sales have been dwindling over a year and the figures have reached below 20k numbers. The 2-wheeler maker also isn't able to grow in the motorcycle category - with its offerings Flame, Jive & Victor already shut down and even Apache, Star Sports/City not performing as per their potential. TVS however is expecting highly from its new 125cc offering 'Pheonix' and as the word (Phoenix) means - TVS expects to rise from the ashes. Notable is to see the Mopeds still contributing to over 40 percent of TVS sales!
5. Yamaha:
When FZ was launched, we expected Yamaha to reach new heights and re-live the era of 'RX'. The model was thought to give Pulsar a strong competition - and in a way it did for a while. But the numbers did not speak as expected - Although FZ sale currently contribute to over 40% of Yamaha sale, the overall sales figure ain't exciting. R15 is clearly the leader in the segment - has not allowed CBR 150/250 take the dominance. With Ray, Yamaha is planning to gain from the growing Scooter love of the Indian consumers.
6. Suzuki:
Suzuki is following Honda's footsteps - focus more on Scooters to gain some ground and later establish itself in Motorcycle category. But, Suzuki got the equation confused! Earlier with Slingshot and later bringing Hayate. Slingshot wasn't even given a chance to compete and then comes the Hayate. Though with strong promotions (led by brand ambassador Salman Khan), Hayate is slowly able to get increased numbers and did its all time high of 9293 units in Nov'12. Access & Swish are loyally giving back to the parent company and combinedly contribute to over 70% of Suzuki sales!
7. Royal Enfield:
Talking numbers wouldn't be right to do for this cult brand. With over six months waiting for most of its models RE is undoubtedly the Harley of India. The new Thunderbird has whipped a storm with its new model and has allowed the brand to garner its all time high sale of 4406 units. Bullet & Electra have been able to perform 2k+ sales in past 6 months. With capacity expansion plans, we expect RE to strengthen to newer heights in coming time.
Monday, December 17, 2012
Indian Auto OEM Social Media Score
Yes, you heard it right! Auto Companies are fighting it out to gain share in not only market sales but in social media as well. OEMs have specialized teams to track consumer engagement in various social media platforms such as Twitter, Facebook, Blogs etc. Engagement is the key to success in these platforms. The brand with continuous interaction and instant response wins in this game. Surprisingly Indian Auto brands fare better than their foreign counterparts here as well. Mahindra leads the pack with over 41 lakh fans of Facebook! The auto brand commands 8% market share, but has succeeded to garner over 25% of the Total Auto fans. Tata and Maruti emerge second and third with 29 Lakh & 22 Lakh fans respectively. Also notable is the popularity of the premium German brands - Audi, BMW & Mercedes.
Audi works its charm in the social media space as well - Audi tops the performance table with an Unmetric score of 53! It symbolifies how well Audi as a brand has engaged with its audience. The score is not a measure of the number of fans alone; but also the brands interaction with its audience through the means of likes, comments, shares and estimated impressions. All of this is possible when the flag bearer is none other than Audi's top boss - Mr. Michael Perschke. This outgoing personality has pumped life into the brand and you'd find him actively involved in most of the discussions as well. In many instances he would himself address customer concerns/queries. Similar character is also visible in Mr. Anand Mahindra - you'd be well aware if you follow his tweet handle regularly.
This is how Engagement Score was calculated -
One could mostly remember the Brand news being dissipated through these forums - perfect channel to announce new launches, product videos and also raise contests. Brands also organize several promotions, surveys and advertisement campaigns through the medium -
So, if you have just liked BMW's page of Facebook - remember that it is being tracked :)
More on the study conducted by Unmetric could be found at - http://www.rushlane.com/mahindra-facebook-fans-tata-1255493.html
Audi works its charm in the social media space as well - Audi tops the performance table with an Unmetric score of 53! It symbolifies how well Audi as a brand has engaged with its audience. The score is not a measure of the number of fans alone; but also the brands interaction with its audience through the means of likes, comments, shares and estimated impressions. All of this is possible when the flag bearer is none other than Audi's top boss - Mr. Michael Perschke. This outgoing personality has pumped life into the brand and you'd find him actively involved in most of the discussions as well. In many instances he would himself address customer concerns/queries. Similar character is also visible in Mr. Anand Mahindra - you'd be well aware if you follow his tweet handle regularly.
This is how Engagement Score was calculated -
click on the image to enlarge
As a layman, one wouldn't be much worried about the scores. But the scores have a much bigger impact than it seems. The phenomena could be explained by assessing the fan profile - 92% of the fans are under the age of 30. This means the probability of the fan converting to a customer is higher in a long term. Also these fans would emerge as 'promoters' of your brand. It is also a way to breed brand loyalists.One could mostly remember the Brand news being dissipated through these forums - perfect channel to announce new launches, product videos and also raise contests. Brands also organize several promotions, surveys and advertisement campaigns through the medium -
So, if you have just liked BMW's page of Facebook - remember that it is being tracked :)
Methodology:
Unmetric compiled its report by sourcing data from its social media benchmark platform. Where brands like Mahindra & Mahindra, Tata Motors and Maruti Suzuki had multiple pages, weighted averages were taken to combine all the data. All statistics were gathered from July 1st, 2012 to September 30th, 2012.
(click to enlarge)
More on the study conducted by Unmetric could be found at - http://www.rushlane.com/mahindra-facebook-fans-tata-1255493.html
Sunday, December 16, 2012
Indian Automotive Print Ads
Print advertisements that made the difference!
Astonishingly you wouldn't find any non-Indian OEM's ad in the list. The understanding of the Indian customer by the Indian Auto makers has made the cut. Majority of the ads in the countdown have made their respective brands a cult of their time and is still admired by many. With time; TV has overtaken Print as the preferred media for the Auto makers and thus the quality of creativity in print ads have deteriorated. Print is now being used by OEM's only to dissipate monthly schemes.
The list starts -
1. Tata Safari :
2. Mahindra Scorpio :
3. Tata Indica (Launch ads) :
Image SOURCE : Team-BHP
4. Tata Nano :
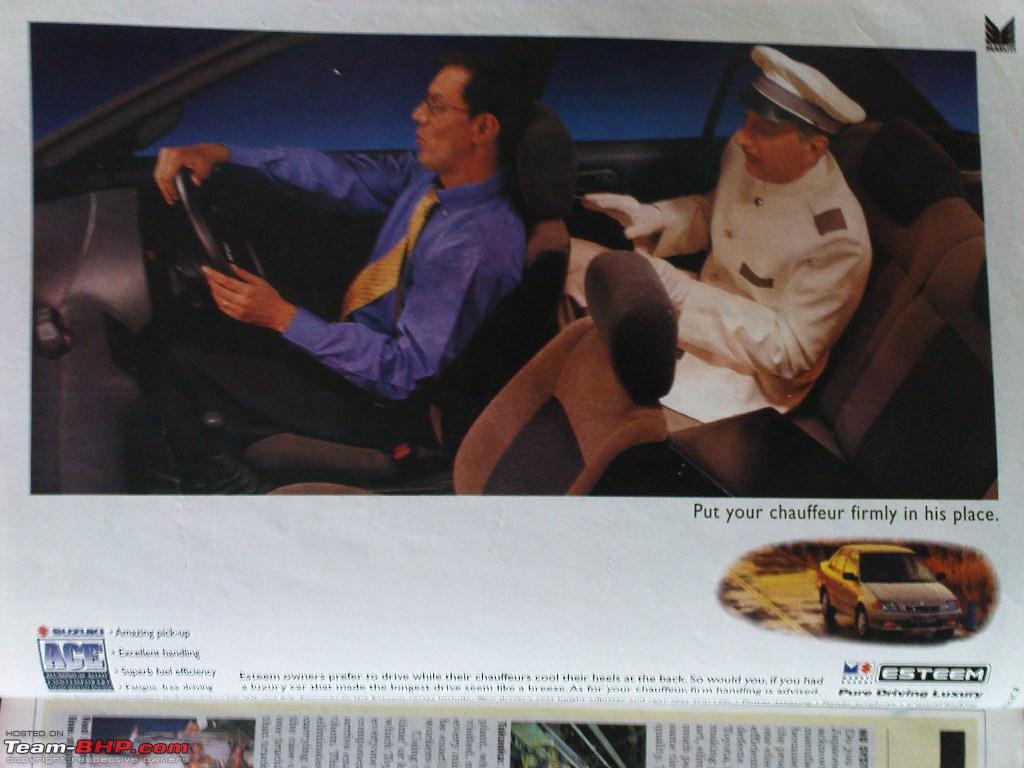
5. Maruti Omni & Esteem (B&W) :
6. Premier Padmini :
7. The Best saved for the last (Mahindra Classic) :
Now that we have re-kindled some old memories, we would want the Auto OEMs to focus on applying their creative instincts back on print ads and hence make their brands immortal in our memory pool. We at Management Punditz strongly feel that print advertisements is an area untouched by foriegn brands and needs immediate attention.
NOTE: Our readers can click on the images to enlarge it to full size.
Wednesday, December 5, 2012
Indian Car Sales Figures - November 2012
November 2012 Sales Figures - Pan India
HIGHLIGHTS:
· 1) November turned out to
be a cracker of month for 2 M’s – Maruti & Mahindra. Diwali celebrations
was not very apparent in the offtake figures for November for other OEMs. With
the year-end falling in the dealers were obviously apprehensive in stocking
vehicles. However November proved to be a good month for Petrol specific models
(namely Alto, i10, Eon). The month also witnessed the launch of the newest
member of Chevrolet family – Sail UVA. Even the top-end SUV Rexton was launched
in markets such as Bangalore, Chennai, Hyderabad & Chandigarh from
M&M’s stable.
·
2) Swift sisters have
undoubtedly been the flag bearers for Maruti. It is one amongst the few brands
to cross Oct’12 offtake (Nov Swift+Dzire – 30837 units v/s Oct – 29822 units).
Alto 800 have bought the much required numbers to Maruti and thus help
retain its leadership; i.e. Alto numbers – 23550 vis-Ã -vis Tata all models
combined – 21119 units, Toyota – 12281 units, Chevrolet – 6746 units, Ford –
7577 units, and list involves all OEMs except Maruti and M&M. In which other
part of the world would we be able to see such kind of dominance!
·
3) Alto has kindled the
trendsetter (what Hyundai terms its Eon). With an aggressive and dynamic
promotional campaign, Eon registered its highest billing numbers for last 6
months in Nov’12 (8449 nos.)! Never in past 6 months, i10 has sold over a 1000
units more than i20. With a near 10k mark (9782 units) i10 figures bring smile
to the Korean automaker. Although with a month-on-month degrowth Verna &
Elantra prove to the segment leaders. The feature rich fluidic designs play a
vital role yet again to establish Hyundai into the premium segment. So, has Elantra truly been a
signature of success? The mentioned graph is self-explanatory:
·
4) Mahindra is the
Maruti of the UV space – this statement turns out true again with M&M
strategically placing products in all price-range. With the entry-level gap
being filled by Quanto, the premium SUV territory is now embarked with Rexton.
The strong product portfolio has made the ‘UV’maker the unshakable no.3 player
in the Indian Automotive space.
·
5) Bolero crosses 10k
figures yet again. Scorpio & XUV record a similar 4.2k figures. Quanto now
seems to be stabilizing at 2.2k to 2.5k mark. With over 12,000 bookings, we
expect the numbers to go higher. But the OEMs intention to increase the
capacity levels for Quanto is not clear as of now. The figures for Xylo &
Verito has been in a ‘reality-check’ mode and hence the lack-luster offtake
(1756 & 1235 units respectively).
·
6) Tata seems to have
lost it completely. The focus for the automaker does not seem clear with its entry
level Nano and its SUV/MUV range. Heavy discounting on its models have a taken
a toll on its brands and Tata’s need to re-work on their strategy on war
footing. The Indica & Indigo family haven’t gained much with the new ev2 or
the club class. Even with the new Storme launched, the Safari numbers remain
stagnant at near 1k figure (1052 units).
·
7) The Duster has
proved to be the Alastair Cook for Renault. Duster alone is contributing to ~80
percent sale of Renault. The brand has set new records and is currently the
largest selling SUV and 13th best selling passenger car in India!!!
The real
·
8) Toyota saw
tremendous dip (by 26%) in its sales. The OEM attributed the plant shutdown for
its lackluster performance.
·
10) With 133 units for
Fabia – it has been the worst offtake for the brand till date. Post Rapid
launch, Skoda’s focus on Fabia has decelerated and thus the outcome. Even Rapid
fails to achieve numbers as per its potential due to the step-motherly
treatment to the brand (promotions majorly shifted to Vento!)
·
11) VW’s unique
promotions and discounts allows the automaker to continue sale momentum for
Polo & Vento. The brands were able to match their October offtake figures.
·
12) Was it the right
time to launch Sail-UVA? This should be the thought of General Motors after
seeing the dip in Beat numbers. Although the Sail-UVA being launched in the
much-hyped Swift/i20 category, the brand hasn’t been able to bring the expected
amount of pull.
13) Honda has over times emerged to be one of the most honky-donky performer - with a fluctuation greater than share prices, the sales of Honda is extremely difficult to monitor. Ex: Honda City which had done 3976 numbers falls to 1218 units within a month! Similar is the case for Brio - from 3700 units to 2199 units.
·
However, December
2012 is ready with a bang to fill excitement in the market with mouth watering
offers –
1.
General Motors
2.
Ford Midnight Sale
& December Dhamaal
4.
Tata Motors December
Delight (discounts upto 1 Lakh)
5.
M&M – discounts
upto 70k
·
Let’s hope the
industry ends the year with a positive note!
A list of Top 20 Brands of the month -


.jpg)